Multi-lender chimney and masonry financing for contractors.
Turn inspections into rebuilds. Ottri is the complete chimney financing platform: one branded application, 20 participating lenders, techs closing at the inspection, the office tracking every application, and funds paid straight to you.
One application. Multiple participating lender programs.
A branded experience from application through funding.
Built for chimney technicians, masons, and offices.
Direct-to-business funding on eligible programs.

Banks and Lenders
20
Finance projects up to
$750K
Full credit coverage
300–850
One application. Eligible lenders, considered in sequence.
Everything a chimney company needs to sell with financing.
Contractor operations
Rebuilds and relining are four- and five-figure surprises. Present monthly payments with the inspection, track every application, and see funded volume.


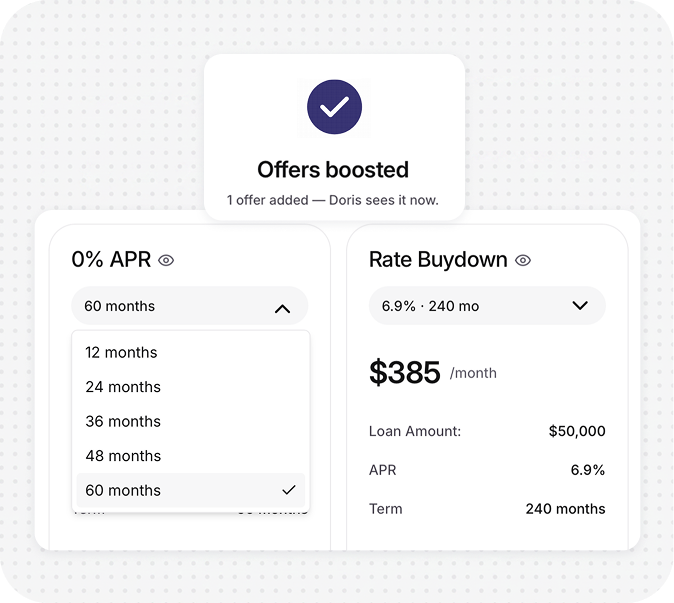
Inspections and performance
Technicians send the application at the inspection by link or QR code. Managers see which techs and entry points turn inspections into repairs.


More financing paths for every chimney and masonry repair.
Financing
Wider Coverage
300 to 850
Reported consumer credit profiles across the Ottri network, with eligibility and options determined by participating lenders.

Project size
Available financing range
$1K to $750K
Support repairs, replacements, renovations, and larger projects through available installment and HELOC programs.
Program and product availability varies by applicant, project, and participating lender.
Homeowners apply on the spot, under your brand, at the inspection.

One application, multiple programs
Homeowners start one application while reviewing the chimney or masonry scope your technician has explained.

Direct-to-business funding
Participating lenders fund your business under the selected program’s funding conditions.

Links, QR codes, and messages
Text or email the application after the chimney inspection.

Homeowner-friendly experience
Give homeowners a clear, mobile-first path to apply and review available options.

Your business stays front and center
Keep your logo, colors, and customer-facing identity throughout the financing flow.

Available promotions
Present seasonal or project-specific promotions where programs allow.
Know what needs action — and which financing tools are working.

See what needs action
Surface applications delayed by missing documents or other required next steps.
Keep follow-up in one place
Open the relevant application, understand the blocker, and continue from one shared pipeline.
Keep applications moving
Give reps clear follow-up signals without asking homeowners to diagnose the financing process.
One lender is a dead end. Twenty is more ways to get the chimney fixed.All in one place.
With
A disconnected process
Separate applications for different lenders.
Application status spread across portals.
Customer handoffs with changing branding.
Follow-up split across people and tools.
Unclear next steps for the team.
With
One application. Participating lender programs.
Applications, offers, and funding status in one place.
Your brand stays present in the financing flow.
A shared financing workspace for your team.
Required next steps visible in the application.
Chimney and masonry financing questions, answered.

Chimney and masonry customer financing lets a homeowner apply for credit toward eligible rebuilds, relining, and repairs through a participating lender. With Ottri, your business presents one branded application and manages financing follow-up in one workspace. Your technicians stay focused on the inspection and the repair; the lender decides whether to extend credit. One branded application reaches 20 participating lenders, so a decline from one lender is not the end of the chimney sale.
Nothing extra for you or your customer. The homeowner fills out one branded application, and Ottri moves it to the next participating lender automatically, across 20 lenders on the Ottri network. Your customer sees one application under your brand the whole way, and you see every step in your dashboard. Each lender makes its own decision.
They may be considered when the defined project fits a participating program's requirements. Describe the inspection findings, the repair or rebuild scope, materials, and labor in the estimate. A crown repair and a full chimney rebuild can have very different amounts; the project, requested amount, homeowner, and participating program determine eligibility. Because one application is considered by multiple lender programs in sequence, a project that does not fit one program can still fit another.
Free to start. No setup fee, no subscription, no demo. Create your account, complete onboarding, and send your first application as soon as your programs are active. Lender and promotional costs, where they apply, depend on the program you choose.
The technician can share the branded application with the inspection report and estimate. Authorized office staff can then review its status and required next steps in Ottri, so follow-up addresses the unfinished financing step rather than asking whether the homeowner is ready. Your business assigns the follow-up; the lender's requirements determine when financing is complete. That shared view is how a fall backlog of inspections turns into scheduled repairs.
Yes, it is your brand from start to finish. Your logo, colors, and contact are on every screen the homeowner sees. We never sell applications as leads. The customer stays yours; the participating lender simply provides the credit, and its required disclosures appear where the law requires.
Update the estimate when opened masonry or a camera inspection reveals additional damage, and confirm whether the lender needs to review the financing amount. The lender takes a fresh look at the larger scope, and the homeowner sees the revised price before the extra work begins. Because status lives in one dashboard, a bigger scope is a quick update, not a restart.
No. A lender's financing decision is a credit decision and says nothing about the condition or safety of the chimney. Your inspection report and the completed repair determine whether the system is ready for use. Keep the safety recommendation and the financing conversation clearly separate with the homeowner. What it does confirm is that the repair can be paid for, so the safety work actually gets done.
The participating lender approves the financing and sets the terms. On eligible programs the lender pays your business directly, so you are never chasing the homeowner for payment. Ottri Global LLC is a licensed loan broker, NMLS 2776988, and is not a lender.
Applying is built to be easy on the homeowner. Whether a program uses a soft or hard inquiry depends on the lender, the product, and the step, and the homeowner sees that information on screen before continuing, so there are no surprises.